France is reportedly in discussions with Qiddiya Investment Company, the leisure subsidiary of Saudi Arabia’s Public Investment Fund, over a potential theme park project at the former Mirapolis site near Cergy in the Île-de-France region.
The plans, first reported by Politico and not yet officially confirmed, are said to involve a project that could exceed €1bn. The concept under discussion is reportedly linked to the Dragon Ball universe, drawing from Qiddiya’s larger project near Riyadh, which was announced with Toei Animation in 2024.
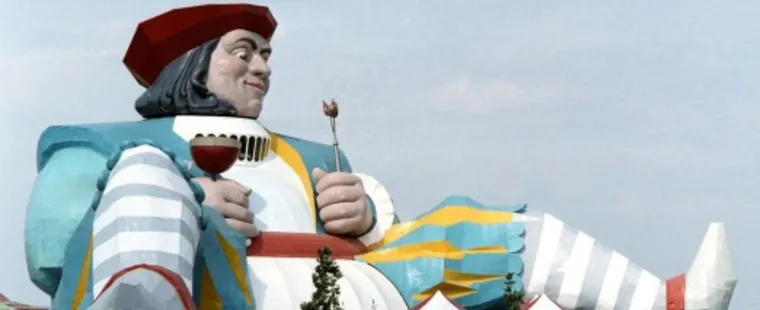
The site has strong historic resonance for the French attractions sector. Mirapolis opened in 1987, backed by Saudi investor Ghaith Pharaon, but closed in 1991 after only four seasons. Any revival of the Courdimanche location would therefore carry commercial opportunity and considerable delivery risk.
For operators, investors and destination planners, the report signals continued appetite for large-scale leisure assets in Europe, particularly where global IP, public infrastructure and sovereign capital intersect.
Europe’s Theme Park Investment Cycle Accelerates
The potential Courdimanche project would enter a highly active European market. The United Kingdom has secured plans for Europe’s first Universal park in Bedford, with public infrastructure funding of around £1.3bn and private investment from Comcast reported at more than £5bn. The resort is scheduled to open in 2031.
France is also seeing substantial activity. Disneyland Paris has advanced its multi-year investment programme, including the relaunch of its second park as Disney Adventure World. Parc Astérix, owned by Compagnie des Alpes, is investing €250m by 2030 following record attendance of 2.95m visitors in 2025.
This context is important. A €1bn project may sound substantial, but in current European resort development it would be an initial threshold rather than a full destination-scale budget. Major operators are increasingly linking attractions with hotels, transport, public realm, food and beverage, retail and multi-day planning to strengthen commercial performance.
Infrastructure And Land Remain Central Questions


French state interest in the Courdimanche site appears to be tied to its location. The former Mirapolis land sits less than one kilometre from Cergy-le-Haut, the western terminus of the RER A. The same line also connects to Marne-la-Vallée, home to Disneyland Paris.
Reports suggest government departments and public agencies have already discussed governance, transport, energy requirements and land control. These areas would be central to any future scheme, particularly given the scale of visitor movement and power demand associated with a major attraction.
Land availability may be the most immediate barrier. Around 30 hectares of the former Mirapolis site has been occupied by a Traveller community since 2017. Previous plans for a tourism eco-village at the location faced environmental and planning issues, while the cancelled EuropaCity project in the same department remains a reminder of the scrutiny attached to new leisure development in Île-de-France.
Destination Planning Beyond The Gate
Mirapolis was largely a day-trip park, with no integrated hotel base. Current sector economics point in a different direction. Destination parks now use accommodation to lengthen stays, increase secondary spend and support stronger year-round demand.
Disneyland Paris has built a large hotel estate over several decades. Parc Astérix is expanding its room stock, while Universal’s Bedford project is expected to open with a 500-room hotel from day one. Cergy-Pontoise’s existing accommodation base is shaped mainly around business and university demand, meaning any major park would need a wider hospitality plan.
For Experience UK’s audience, the reported Qiddiya project is significant because it brings together IP strategy, sovereign investment, transport planning, land politics and resort economics. If progressed, it could become one of Europe’s most closely watched attraction developments, but its viability will depend on far more than a headline investment figure.


